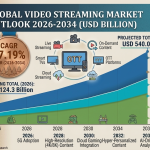
According to IMARC Group, the global video streaming market was valued at USD 124.3 billion in 2025 and is projected to reach USD 540.0 billion by 2034, growing at a CAGR of 17.19% from 2026 to 2034. This explosive expansion reflects the convergence of better infrastructure, richer content ecosystems, and a consumer base that increasingly expects entertainment on demand, anywhere, on any screen.
Video Streaming Market Size & Key Statistics
Below are the key video streaming market share and size statistics drawn from IMARC Group's comprehensive market analysis:
Report Attributes & Key Statistics
Base Year - 2025
Historical Period - 2020–2025
Forecast Period - 2026–2034
Market Size in 2025 - USD 124.3 Billion
Market Forecast in 2034 - USD 540.0 Billion
Market Growth Rate (2026–2034) - 17.19% CAGR
Largest Region - North America
Request for a Sample Report for Detailed Video Streaming Market Share Evaluation: https://www.imarcgroup.com/video-streaming-market/requestsample
Video Streaming Industry Overview
The video streaming market growth story is built on a fundamental shift in how consumers access and pay for video content. Video streaming encompasses the delivery of on-demand and live video over the internet, eliminating the need for physical media or scheduled broadcast programming. Services range from subscription-based OTT platforms (Netflix, Amazon Prime Video, Disney+) and transactional video-on-demand to free ad-supported streaming and live linear television over the internet.
The market spans a complex value chain, including content creation, content delivery networks (CDNs), encoding and transcoding platforms, monetization technology, and device ecosystems. As broadband penetration deepens globally and 5G networks lower latency and increase mobile bandwidth, streaming quality and accessibility have both improved substantially — drawing hundreds of millions of new subscribers across emerging markets in Asia Pacific, Latin America, and the Middle East.
Key Market Drivers & Trends in 2026
Several powerful forces are shaping the video streaming market and fueling its accelerated growth trajectory:
5G Rollout and Infrastructure Expansion
The global deployment of 5G networks is dramatically expanding the ceiling for mobile streaming quality, enabling 4K and HDR content delivery on smartphones without buffering. Combined with high-speed fixed broadband adoption — 79% of U.S. adults had home broadband by 2023 — network infrastructure is removing the last friction points in the streaming experience.
Cord-Cutting and Shift from Linear Television
Traditional pay-TV subscriber bases continue to erode as consumers, particularly younger demographics, migrate to on-demand platforms. This structural cord-cutting trend is accelerating investment in streaming-first content strategies by both legacy media companies and technology giants, expanding content libraries and driving subscriber acquisition.
Investment in Original and International Content
Leading platforms are committing billions annually to original programming and locally produced international content. Netflix, Amazon, and Apple TV+ compete fiercely for exclusive IP and talent, while European and Asian producers are gaining global audiences — European-made content accounts for 30% of SVOD viewing time on major platforms across the EU.
Diversification of Revenue Models
Streaming platforms are expanding beyond pure subscription models, introducing ad-supported tiers (AVOD), bundled offerings, and mobile-only plans at lower price points. This diversification is unlocking price-sensitive markets and driving subscriber growth in emerging economies where USD 10–15/month SVOD pricing remains a barrier.
Integration of VR, AR, and Immersive Technologies
The next frontier for video streaming is immersive content delivery through virtual and augmented reality. Early adoption by sports broadcasters and live event producers is establishing use cases for spatial video, while device ecosystems (Apple Vision Pro, Meta Quest) are creating new demand for volumetric and 360-degree streaming content.
Cloud Computing and CDN Advancements
Cloud-native video infrastructure enables platforms to scale globally without capital-intensive owned data centers. Advances in adaptive bitrate streaming, edge computing, and AI-driven content recommendation are simultaneously reducing delivery costs and improving viewer experience, compounding both reach and monetization.
Key Market Segmentation
The video streaming market is segmented by component, streaming type, revenue model, and end user. Understanding video streaming market share by segment reveals where adoption is most concentrated and where the next growth inflection points lie.
By Component
- Solution (Largest) — IPTV, OTT, Pay TV
- Services
- Consulting
- Managed Services
- Training & Support
By Streaming Type
- Live / Linear (Dominant)
- Non-Linear / On-Demand
By Revenue Model
- Subscription / SVOD (Leading)
- Transactional / TVOD
- Advertisement / AVOD
- Hybrid
By End User
- Personal (Dominant)
- Commercial
Solution Segment — Largest by Component
The solution segment — encompassing IPTV, over-the-top (OTT), and pay TV platforms — commands the largest share of the market. OTT platforms have emerged as the primary growth driver within this segment, as they bypass traditional broadcast infrastructure and reach viewers directly over broadband internet. This low-barrier global reach enables platforms to scale subscriber bases across dozens of countries without country-specific broadcast licenses or network infrastructure investments.
Subscription Model — Leading Revenue Approach
Subscription-based video-on-demand (SVOD) is the dominant revenue model, generating predictable recurring revenue that funds ongoing content investment. U.S. households spent an average of USD 61 per month on SVOD services in 2023, while Asia Pacific SVOD subscriptions are projected to grow from 594 million in 2023 to 687 million by 2029 — adding 93 million new subscribers in six years.
Regional Market Analysis
The following regional breakdown maps the key dynamics shaping video streaming market growth across geographies:
|
Region |
Key Highlights |
|
North America Largest |
United States and Canada; 331.1M internet users with 97.1% penetration; streaming at 41.4% of total TV usage (July 2024); 235M streaming video subscribers (2023); 79% household broadband penetration; home to major global platforms including Netflix, Hulu, Amazon Prime Video, and Apple TV+ |
|
Europe |
Netflix, Prime Video, and Disney+ account for 85% of streaming viewership; EU-mandated European content quotas driving local production; European titles account for ~21% of SVOD viewing time; Germany, France, UK, Italy, Spain among key markets |
|
Asia Pacific |
SVOD subscriptions rising to 687M by 2029; China projected at 378M subscriptions by 2029; USD 49B projected SVOD revenue by 2029; rising medical tourism driving content localization demand; India, Japan, South Korea, Australia, Indonesia as growth markets |
|
Latin America |
Mexico 96.9% and Brazil 95.8% streaming adoption (GWI); Brazil is the largest LatAm market; growing middle class and smartphone adoption driving SVOD uptake; hybrid and AVOD models gaining traction |
|
Middle East & Africa |
Saudi Arabia saw 20% streaming subscription growth in 2023; 4G/5G expansion enabling mobile-first streaming; tech-savvy young consumer base; UAE and South Africa as key market anchors; healthcare and sports streaming among fastest-growing verticals |
Leading Players in the Video Streaming Industry
The global video streaming market features a mix of technology giants, media conglomerates, and specialized infrastructure providers. These companies compete across content, technology, and distribution — making the competitive landscape both broad and deeply consolidated at the top. Key companies covered in the IMARC Group report include:
Connect for Detailed Video Streaming Market Share Segmentation Analysis – Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=4211&flag=C
Latest Industry Developments
- November 2024 — Bending Spoons & Brightcove
Bending Spoons, the Italian mobile software company behind Evernote and Lensa, acquired Brightcove Inc. — a leading cloud video platform for enterprise media — in an all-cash deal worth approximately USD 233 million, signaling consolidation in the B2B streaming infrastructure segment.
- November 2024 — Comcast / NBCUniversal
Comcast announced plans to spin off NBCUniversal's cable networks and select digital assets into a new independent company, "SpinCo," targeting approximately 70 million U.S. households and marking one of the most significant restructurings in American media in years.
- September 2024 — Hallmark+
Hallmark Media launched Hallmark+, its dedicated streaming service priced at USD 7.99 per month or USD 79.99 annually, entering the competitive SVOD marketplace with its established brand identity around holiday and family-oriented programming.
- August 2024 — Bharti Airtel & Apple
Bharti Airtel and Apple forged a partnership to offer Apple TV+ access to Airtel Xstream customers across India, deepening streaming penetration in one of the world's largest and fastest-growing mobile internet markets.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Retail, Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104